
MERCADOS
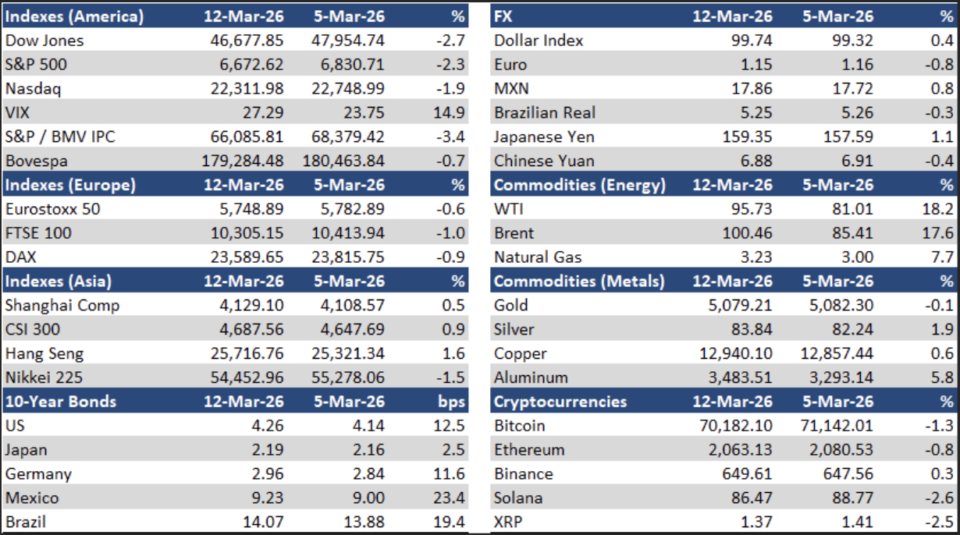
En S&P / BMV IPC fell another 3.4% over the week amid rising oil prices and continued global risk aversion triggered by the Middle East conflict. Meanwhile, the Mexican peso lost 0.8% to close at MXN$17.86/USD; the yield of the 10-year M-Bono was up 23 bps to 9.23%.
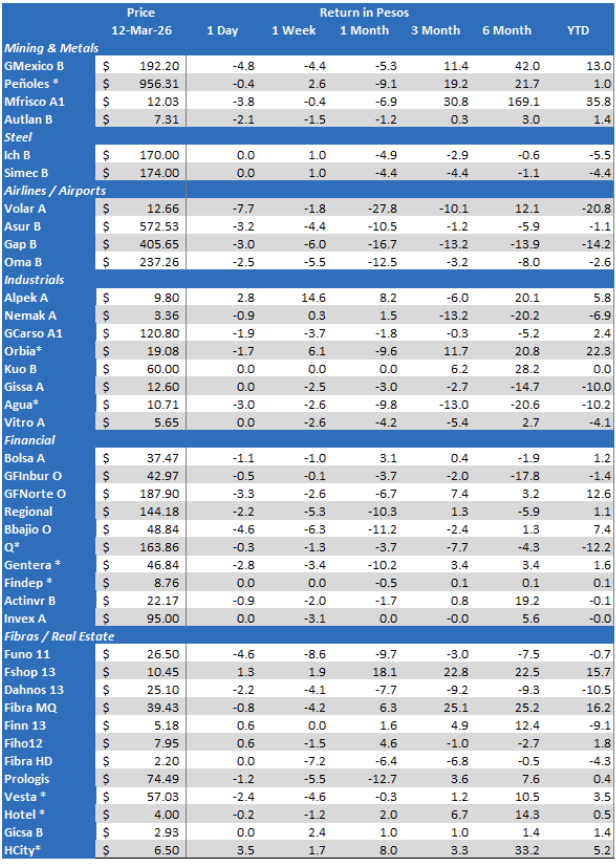
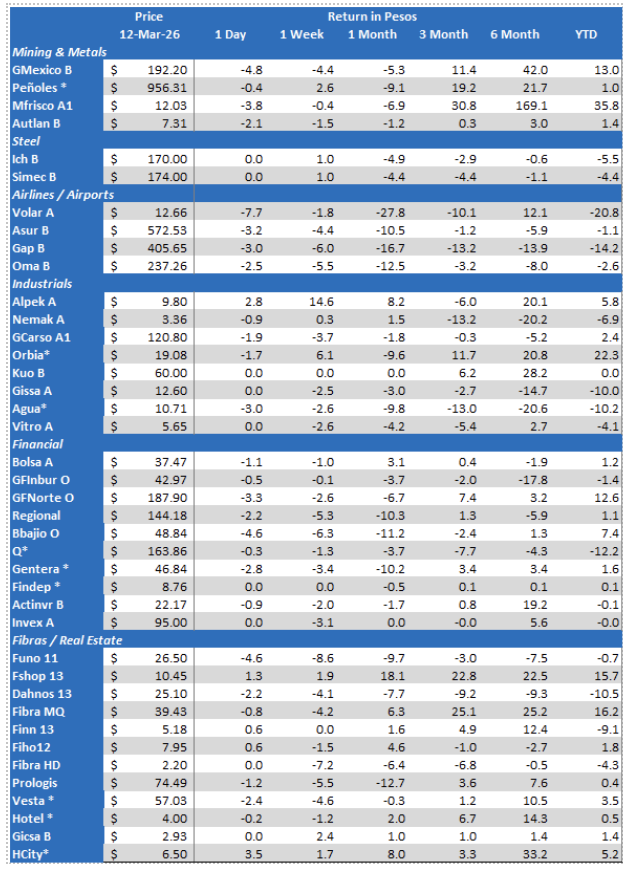
En S&P / BMV IPC's top weekly gainers were: ORBIA* (+6.1%), PEÑOLES* (+2.6%), and TLEVISA CPO (+2.0%). On the other hand, the main weekly losers were: SIGMAF A (-7.2%), MEGA CPO (-6.7%) and CEMEX CPO (-6.6%).
EMPRESAS COTIZADAS
Tiendas 3B reported mixed results with strong top-line growth but a larger net loss due to extraordinary items. Total revenues increased 34.4% YoY, supported by rapid network expansion and resilient consumer demand, while the company opened 184 net new stores during the quarter and 574 over the year, reaching 3,346 units by year-end and continuing to scale its discount format across Mexico. SSS grew 16.6% YoY, decelerating slightly from the 17.9% growth reported in 3Q25, although still reflecting strong traffic and basket dynamics driven by the company’s value proposition. Gross profit increased 32.7% YoY, broadly tracking revenue growth, while the gross margin contracted 21 bps as higher logistics costs associated with the opening of new distribution centers weighed on profitability. Reported EBITDA fell 90% YoY as the company recorded a MXN$891 million non-cash share-based payment expense and a MXN$230 million one-time write-off of an account receivable relating to the termination of the payment terminal provider. Adjusted EBITDA excluding extraordinary items rose 23.5% YoY, although the adjusted EBITDA margin declined 48 bps to 5.5% due to the impact of logistics costs and investments to support expansion. The net loss widened to MXN$1.0 billion in 4Q25, from MXN$24 million in 4Q24. For 2026, the company expects SSS growth of 13–16% and total sales growth of 29–32%. It also projects between 590 and 630 new store openings during the period.
Cemex is in the process of divesting certain operations in Colombia. The divestment is expected to take place through several separate transactions with different parties, for a combined purchase price of approximately US$555 million, at an approximate 10x multiple of 2025 EBITDA.
Fibra Mty completed a US$488 million follow-on equity offering. Fibra Mty intends to use the net proceeds primarily to invest in industrial properties.
Femsa announced the closing of the merger between BradyPLUS and Imperial Dade. Femsa holds an approximately 19% stake in the combined company and will have representation on its board of directors.
Gap’s total passenger traffic declined 5.5% YoY to 4.6 million in February, with domestic traffic falling 4.5% to 2.5 million and international traffic decreasing 6.6% YoY to 2.1 million.
Oma’s total passenger traffic increased 5.4% YoY in February, with domestic traffic rising 6.5% and international traffic falling 0.3%.
Volaris’ total passenger traffic increased 4.1% YoY to 2.3 million in February 2026, with domestic traffic rising 0.4% and international traffic up 14.7%. RPM’s were 1.5% YoY higher as ASM’s advanced 1.0% and the load factor improved 0.5 PP to 85.7%.
Quálitas maintained its leadership in the Mexican auto insurance market, with a 33.9% share of written premiums (vs. 34.1% in 2024) and a 36.2% share of earned premiums in 2025, according to the latest Automobile Insurance Industry Report. Quálitas posted a combined ratio of 92.2% in 2025 (vs. 90.0% in 2024). The industry reported a combined ratio of 95.8% in 2025 (vs. 94.9% in 2024).
Corporativo GBM appointed Fernando Ramos González de Castilla as its new CEO, following approval by the Ordinary and Extraordinary General Shareholders’ Meeting. The company repurchased 9.5 million shares as part of its incentive plan.
AMX’s Claro Sports expanded its broadcasting rights for the UEFA Europa League and UEFA Europa Conference League for the 2026–2027 season. Coverage will begin with the round of 16 matches on March 12.
Sitios Latinoamérica announced that shareholders subscribed and paid for 576,834,234 shares, equivalent to 96.14% of the total shares offered in the first pre-emptive rights offering running from February 23rd to March 9th, 2026. As a result, 23,165,766 shares, representing 3.86% of the issuance, remain unsubscribed. The company raised MXN$2.88 billion with this transaction.
RLH Properties has entered into a MXN$500 million secured term loan with Banco Actinver. The credit facility is backed, among other assets, by real estate owned by the company and its subsidiary Mandarina III. RLH Properties will use proceeds for general corporate purposes.
S&P Dow Jones Indices announced preliminary results for the new composition of the S&P / BMC IPC, including the incorporation of VOLAR A in substitution of CUERVO *. Final results will be announced next Friday March 13th at the close with changes effective on March 23rd.
Grupo La Comer opened Fresko Mérida, its first store in the state of Yucatán, through a MXN$885 million investment that will create 370 formal jobs, 260 direct and 110 indirect. With this opening, the company now has 93 stores operating nationwide and continues its expansion in southeastern Mexico.
OTRAS EMPRESAS
Banco Ualá launched a trading service in its mobile app, which will allow Mexican users to acquire fractioned US shares from MXN$20.0. It will include educational content.
ECONÓMICO
Headline inflation increased 0.50% MoM in February 2026, above the Citi Mexico Expectations Survey consensus projection of 0.43%. Core inflation increased 0.46% (in line with expectations), driven by higher merchandise and services prices, particularly processed foods and education services. The monthly non-core inflation rate rose 0.64%, primarily reflecting higher fruit and vegetable prices. On an annual basis, headline inflation stood at 4.02% (vs. the 3.95% forecast), a level not seen since December 2024 and above Banco de Mexico’s tolerance interval. The core inflation reached 4.50% (in line).
Formal IMSS registered jobs increased by 182,778 in February, the highest level on record for a similar month. As a result, total affiliated employees reached 22.7 million, up 1.2% YoY.
Light vehicles sales declined 0.3% to 118,305 units in February 2026, while production fell 1.8% to 311,457 units and exports were down 4.4% to 247,945 units, according to INEGI.
International visitors increased 10.0% YoY to 8.8 million in January, according to INEGI. Total expenditure grew 3.9% to US$3.48 billion, but the average expenditure was down 5.5% to US$393.4.
Light vehicle sales fell 0.3% to 118,305 units in February, according to INEGI. Production declined 1.8% to 311,457 units while exports were down 4.4% to 247,945 units.
Heavy vehicle sales declined 38.9% YoY to 2,303 units in February, according to INEGI. Production fell 49.1% to 6,974 units while exports decreased 32.0% to 7,849 units.
Total credit of the banking system grew 6.0% YoY in January, driven by solid expansion in consumer (+12.4% YoY) and corporate credit (+6.0% YoY), while mortgage lending increased 5.4% YoY, financial institutions declined 0.4% YoY, and government contracted 8.1% YoY. Asset quality remained solid, with the NPL ratio at 2.22%, from 2.02% a year earlier, and a 146.3% coverage, from 156.4%. The capitalization ratio reached 20.2%. The sector reported total monthly net profits of MXN$28.36 billion, representing 3.7% YoY growth. ROE declined to 17.2%, from 18.1% last year, while ROA remained at 2.0%.
On-line sales increased by 19.1% to MXN$941 billion in 2025, according to the Mexican Association of On-line Sales. They represented 17.7% of total retail sales.
The latest Citi Mexico Expectations Survey indicates that the median forecast expects a 25-bps cut in Banco de Mexico’s key interest rate in the March meeting, shifting from the previous survey where the median pointed to a cut in May. The policy rate expectation for both YE26 and YE27 remained unchanged at 6.5%. The 2026 GDP growth forecast increased to 1.5%, from 1.4% previously, while the 2027 projection remained unchanged at 1.8%. The headline inflation expectation for YE26 remained at 4.0%, while the core inflation forecast was revised upwards to 4.20% from 4.15%. The headline inflation estimate for YE27 rose to 3.78%, from 3.73% previously, while the core inflation projection increased to 3.76%, from 3.74%. The peso projection strengthened marginally with the USDMXN expected to close at 18.18 by YE26 versus 18.20, while the YE27 projection improved to 18.70, from 18.76 previously.
The Mexican government renewed its agreement with 96% of gasoline retailers to maintain maximum regular gasoline prices at MXN$24.0/liter over the next 6 months.
Subasta CETES: 28-day CETES -0 bps to 6.81%; 91-day CETES -2 bps to 7.08%; 175-day CETES -2 bps to 7.09% and 707-day CETES +27 bps to 7.81%.
Descargar PDF: Mexican Market Chatter March 5th – March 12th